The Florida Roof Insurance Claim Guide
Deadlines, deductibles, and your rights — in plain English, from a roofer who's seen what happens when homeowners don't know them.
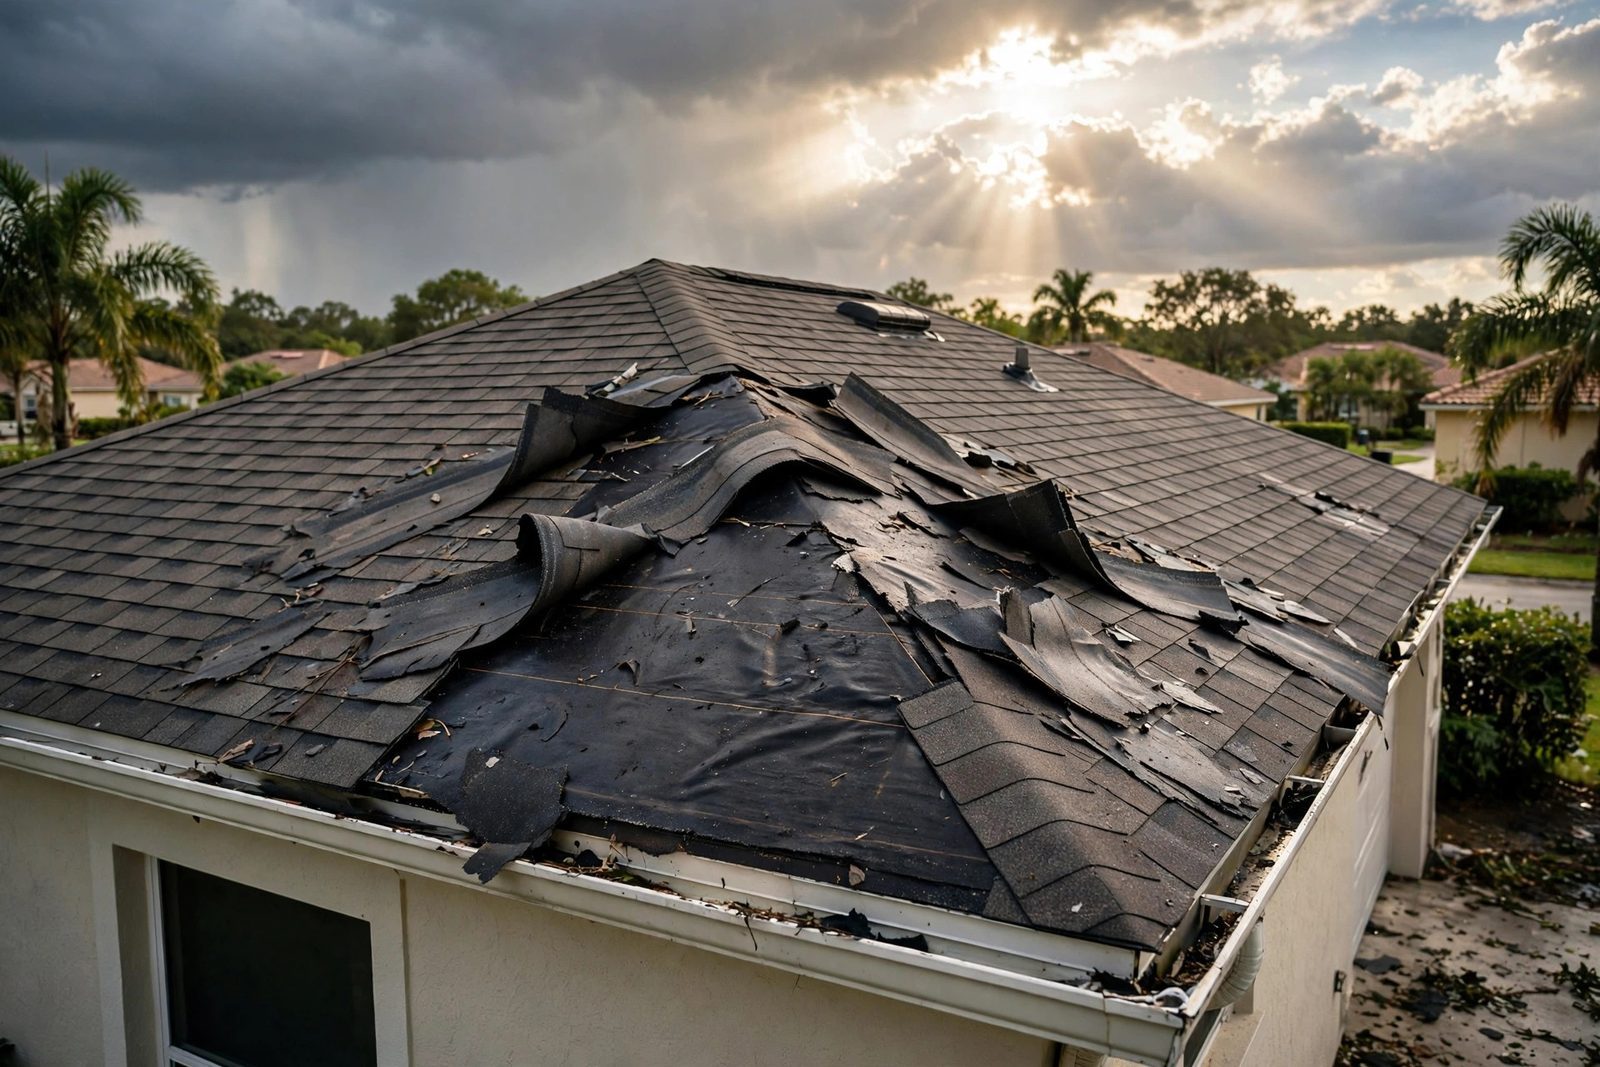
The timeline that controls everything
| Deadline | What it means |
|---|---|
| 1 year | File your initial (or reopened) claim within a year of the storm (§627.70132). |
| 18 months | Window for supplemental claims — damage discovered later. |
| 60 days | Your insurer must pay or deny once they have your proof of loss (§627.70131). |
| 2 years | Statute of limitations if a dispute becomes a lawsuit (HB 837). |
The first two are the killers. Miss them and the claim is gone no matter how real the damage.
Before the adjuster arrives
- Photograph everything — roof from the ground, every interior stain and leak, damaged belongings. Timestamped phone photos count.
- Mitigate — tarp it, move things, stop the bleeding. Insurers expect mitigation; it never hurts the claim.
- Get an independent assessment — our storm damage inspection documents what's storm-created versus wear, with photos and a written report, before anyone from the insurance company sets foot on your roof.
- Read your Loss Settlement clause — specifically whether your roof is covered at replacement cost or actual cash value (see below).
Three things that surprise homeowners
Your hurricane deductible isn't $1,000. Most Florida policies carry a 2%, 5%, or 10% hurricane deductible on dwelling coverage. On a $400,000 home, 2% is $8,000 out of pocket before insurance pays a dime. It applies once per calendar year.
Your roof might be covered at depreciated value. Many policies flip roofs to actual cash value around year 10. A 12-year-old shingle roof at ~48% depreciation yields a check far smaller than the replacement bid. This is the #1 post-storm surprise in Florida — and it's in your policy today, whether you've read it or not.
You can't sign your claim away. For policies issued or renewed since January 1, 2023, assignment-of-benefits agreements are void in Florida. Any contractor asking you to sign an AOB is asking for something the law won't enforce. We never will.
Wear and tear vs. storm damage
Insurers cover sudden, accidental damage — not aging. "Your roof is old" is the most common denial reason in Florida, and sometimes it's legitimate. The defense is documentation: dated photos of storm-created damage (freshly lifted shingles, impact marks, displaced flashing), ideally from an inspection done before the adjuster arrives. "It leaked after the hurricane and never before" is a story; photos are evidence.
If your claim is denied or underpaid
You can request reinspection, file a supplemental claim within 18 months, complain to the Florida Department of Financial Services, hire a public adjuster, or consult an attorney — in roughly that order of escalation. What helps at every stage: the documentation you created before the adjuster arrived.
Storm damage? Start with documentation, not paperwork. Call (754) 240-2335 — we'll inspect, photograph, and give you an honest read on whether a claim makes sense given your deductible, before you file anything.
Official resources
- Florida Department of Financial Services — file complaints and verify adjuster licenses.
- Florida Office of Insurance Regulation — rate filings, market conduct, and the OIR-B1-1802 wind mitigation form.
Should I file a claim for every leak after a storm?
A: Not automatically. Do the math first: is the likely covered damage well above your hurricane deductible? Filing a small claim that nets you little can still count as claims history. We'll give you an honest damage assessment so you decide with numbers.
The adjuster's estimate is way below my contractor's. Now what?
A: This is common — adjuster estimating software and real HVHZ-compliant construction don't always agree. Supplemental claims exist for exactly this: documented, code-required costs the first estimate missed.
Can my insurer drop me for filing a storm claim?
A: Florida's 15-year rule (§627.7011) bars insurers from refusing to renew solely because of roof age under 15 — but claims history, overall condition, and other factors still count. One more reason to file only claims that make financial sense.
Roof Trouble? Call Now — We Answer 24/7
One call gets you a free inspection, photos of exactly what your roof needs, and a straight written quote. No forms, no waiting — a real person picks up.
● Open now — nights, weekends & holidays